
Full expensing
Maximise your investment and protect your cash flow
Running a professional kitchen has never been more demanding. From tightening budgets to soaring energy costs, every penny counts. But protecting your cash flow shouldn't mean compromising on the reliability of your refrigeration during a busy service.
The UK government's full expensing scheme is a permanent tax relief policy designed to boost business investment, giving you long-term certainty when upgrading to highly efficient, cost-effective equipment.
What is full expensing?
Full expensing offers 100% first-year capital allowances on qualifying new and unused main rate plant and machinery.
For qualifying limited companies, this can deliver up to a 25p reduction in Corporation Tax for every £1 invested in qualifying kitchen equipment, depending on your company's applicable Corporation Tax rate and profitability.
How does full expensing benefit your business?
When buying a new fridge, looking only at the purchase price is tempting. However, the purchase price typically accounts for only 20% of the total lifetime cost—the real expense lies in running it.
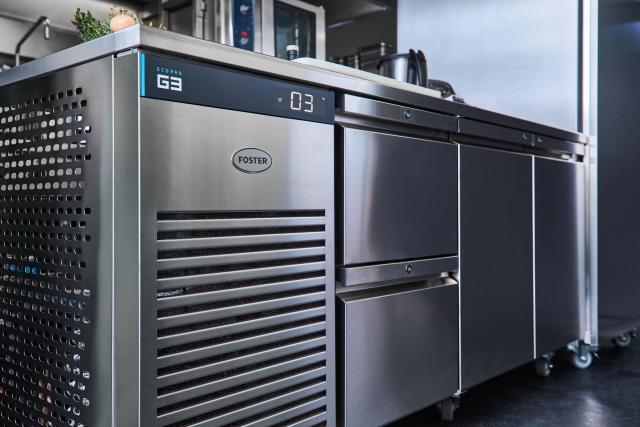
Full expensing allows eligible companies to deduct the full qualifying cost of the investment from taxable profits in the year of purchase rather than spreading relief over several years. This means you can invest in highly energy-efficient Foster equipment—like our EcoPro G3 range—to lower energy bills, reduce your long-term Total Cost of Ownership (TCO), and benefit from immediate tax relief.
What is a capital allowance?
Capital allowances allow businesses to deduct some or all of the cost of qualifying capital assets from their profits before calculating tax.
Alongside full expensing, other capital allowances include the Annual Investment Allowance (AIA)—which also offers up to 100% upfront relief on qualifying expenditure—Writing Down Allowances (WDAs), and First-Year Allowances (FYAs).
Who is eligible?
- Business structure: Full expensing applies strictly to companies subject to Corporation Tax. (Unincorporated businesses, such as sole traders and standard partnerships, can generally achieve equivalent 100% first-year relief via the Annual Investment Allowance).
- Asset condition: Equipment must be bought new and unused to qualify for full expensing.
Maximise your savings with flexible finance
You can pair your equipment upgrade with our 0% interest-free credit scheme.
Under HMRC rules, qualifying hire purchase and credit-sale agreements allow businesses to claim capital allowances in year one while spreading payments over 12 or 24 months. This means your new refrigeration can start paying for itself on the cookline before the equipment is fully paid off.
Tax treatment depends on your individual business circumstances and may be subject to change. Always consult a qualified accountant or tax professional, or visit GOV.UK's Capital Allowances Guidance for full eligibility criteria.